Equity Compensation Explained: RSUs, Stock Options and Offer Value
Equity can be a large part of an offer or a number that never turns into money. This post explains how RSUs and stock options work, when each is taxed under federal rules, and which questions tell you what a grant is realistically worth.
Steven Schulz
· 7 min read
Equity in an offer letter is a promise of future ownership, with conditions attached. Whether it is worth as much as the recruiter's spreadsheet says depends on three things: what kind of grant it is, whether the shares can be sold, and how it is taxed. This post covers the common forms and the federal tax rules as of late 2026. It is general information; state rules differ, and a large grant is a good reason to pay a tax professional.
Two families: RSUs and options
Almost every equity grant in a job offer is one of two things.
Restricted stock units (RSUs) are a promise to give you shares in the future, free, once you meet the vesting conditions. An RSU is worth something as long as the share price is above zero.
Stock options are the right to buy shares later at a price fixed today, the strike or exercise price. An option is worth something only if the share price rises above the strike, and you have to pay to turn it into shares.
Public companies and late-stage private companies mostly grant RSUs. Early and mid-stage startups mostly grant options. You will meet both in listings for roles such as software engineer or product manager.
Vesting: when it becomes yours
Vesting is the schedule on which you earn the grant. Leave before a portion has vested and you lose that portion.
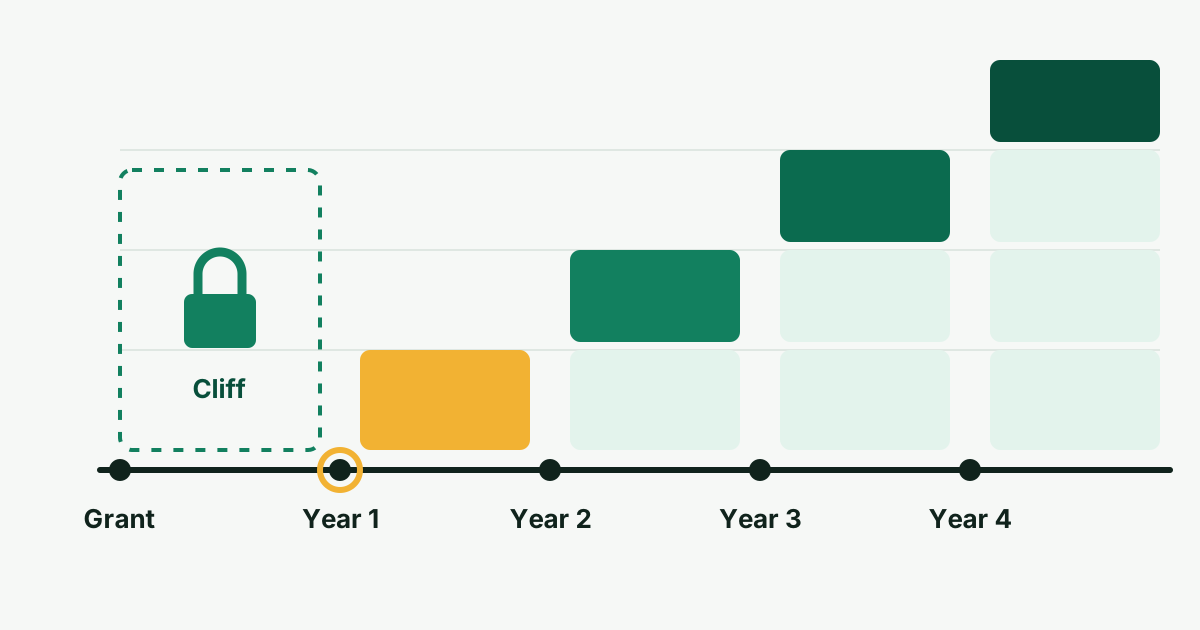
- Four years with a one-year cliff is the traditional pattern: nothing vests for the first 12 months, then a quarter vests at once, and the rest vests monthly or quarterly over the following three years.
- No cliff, quarterly from the start is common for RSUs at large public companies.
- Back-loaded schedules exist. A grant that vests 10 percent in year one and 40 percent in year four is worth far less to someone who may leave after two years.
- Refresh grants are additional grants made in later years. Ask whether they are standard practice; without them your pay drops when the initial grant runs out.
RSUs: simple at public companies, less so at private ones
At a public company, RSUs behave like a delayed stock bonus. When shares vest, their market value on that day is ordinary wage income, reported on your W-2 like salary. The IRS treats this under the rules for restricted property: you include the fair market value in income in the year it becomes substantially vested, and your holding period for capital gains starts then (Publication 525).
Your employer withholds tax at vesting, usually by keeping back some of the shares. For federal income tax, employers commonly use the flat rate for supplemental wages, which the IRS sets at 22 percent, or 37 percent on supplemental wages above $1 million in a calendar year (Publication 15). If your actual tax bracket is higher than 22 percent, the withholding falls short and you owe the difference when you file. State tax applies on top; see remote work and state taxes for which state that is.
After vesting you simply own shares. Sell at once and there is little or no additional gain. Hold, and any later rise or fall is a capital gain or loss, long-term if you held the shares for more than one year after vesting (IRS Topic 409).
Private-company RSUs usually carry a second condition: they vest only if you meet the time requirement and the company has a liquidity event such as an IPO or sale. This "double trigger" spares you a tax bill on shares you cannot sell. It also means the RSUs may expire worthless if no such event happens within the grant's term, and that you may lose them if you leave before it.
Stock options: ISOs and NSOs
Options come in two tax flavors. Your grant document says which you have.
| Incentive stock options (ISOs) | Nonqualified stock options (NSOs) | |
|---|---|---|
| Who can receive them | Employees only | Employees, contractors, advisors |
| Tax at grant | None | Generally none |
| Regular tax at exercise | None | Spread is ordinary wage income |
| Other tax at exercise | Spread may count for AMT | Payroll taxes for employees |
| Tax at sale | Capital gain if holding periods are met | Capital gain or loss on change after exercise |
The spread is the difference between the share's fair market value on the day you exercise and the strike price you pay.
NSOs
With a typical nonqualified option, nothing is taxed at grant. When you exercise, the spread is compensation income, even if you cannot sell the shares (IRS Topic 427). At a private company that means paying the strike price and a tax bill, in cash, for stock with no market.
ISOs
With an incentive stock option you generally include nothing in regular income at grant or at exercise. If you then hold the shares until at least two years after the grant date and one year after exercise, the entire gain over the strike price is long-term capital gain. Sell earlier and the spread at exercise (or your actual gain, if lower) becomes ordinary income.
The catch is the alternative minimum tax. The spread at exercise is an adjustment for AMT purposes in the year you exercise, unless you sell the shares in the same year (IRS Topic 556 describes the AMT; the ISO adjustment is explained in Publication 525). It is possible to exercise, hold, watch the price fall, and still owe AMT on a paper gain that no longer exists. Before exercising a meaningful number of ISOs, have someone run the AMT calculation.
Two further ISO rules worth knowing: to keep ISO treatment you must exercise no later than three months after your employment ends, and only $100,000 worth of stock, measured at grant, can first become exercisable as ISOs in any calendar year; the excess is treated as NSOs.
The exercise window
When you leave a company, vested options do not stay open forever. Many plans give you 90 days to exercise or forfeit, which lines up with the three-month ISO rule. Some companies offer windows of several years; the options then lose ISO status after three months but remain exercisable. If you could not afford to buy your shares on short notice, a long window is one of the most valuable terms in a grant.
Early exercise and the 83(b) election
Some startups let you exercise options before they vest. You then hold restricted stock that the company can buy back if you leave. Normally the gain would be taxed as each portion vests. A section 83(b) election lets you instead be taxed at the time of transfer, when the spread may be zero or tiny, so that later growth is capital gain.
The deadline is strict: the election must be filed with the IRS no later than 30 days after the transfer, and it generally cannot be revoked (Publication 525; the IRS provides Form 15620 for it). If you make the election and later forfeit the shares, you do not get back the tax you paid. The election does not apply to unexercised options or to standard RSUs.
Employee stock purchase plans
Public companies often offer an ESPP alongside RSUs: you set aside part of each paycheck and buy company shares at a discount at the end of a purchase period. Under a qualified plan the discount can be up to 15 percent, and purchase rights are capped at $25,000 of stock per calendar year, valued at the grant date. Tax is due when you sell, and how the discount is taxed depends on how long you held the shares.
What a grant is realistically worth
For public-company RSUs, the arithmetic is honest: shares vesting per year times the current price, less tax. The risk is the share price.
For private-company equity, the number on the offer is an estimate built on assumptions. To judge it you need facts the offer letter rarely includes. Ask:
- How many shares or options, and how many fully diluted shares are outstanding? A share count alone is meaningless; the percentage is what matters.
- What is the strike price, and what was the preferred share price in the last funding round?
- When was the last independent valuation of the common stock, and what was the result?
- What is the vesting schedule and the post-termination exercise window?
- Does anything accelerate on a sale of the company?
Then discount. The preferred price paid by investors is not the value of your common shares. Most startups do not reach an exit that pays common shareholders well. A sensible habit is to decide whether the offer works on salary alone, and to treat private equity as upside, not as part of the rent.
When comparing offers, put each on the same footing: base, expected bonus, and equity per year under the real vesting schedule, with private equity marked down heavily. Posted ranges and the salary pages generally show base pay only; see how to read the salary range in a job posting.
What to do next
Get the grant terms in writing before you accept: type of equity, number of shares, strike price if any, vesting schedule and exercise window. Work out the per-year value under the real schedule, and for private companies ask the five questions above. Equity is negotiable more often than people think; how to raise it is in negotiating a remote job offer. And before you exercise options or sell a large block of shares, talk to a tax professional with the grant documents in hand.